Q4 Update: The De-Risking

Nothing discussed/written should be considered as investment advice. Please do your own research or speak to a financial advisor before putting a dime of your money into these crazy markets. In other words, if you buy something I bought, you deserve to lose your money.

The only reason why I am making my portfolio public because it provides accountability to me. Some or all the analysis I provide could be from the top of my head and should not be considered accurate.

My investing goal is simple; to try to manage risk while being fully invested without market timing. Howard Marks said it best, “even though we can’t predict, we can prepare.”

All my references to the Market are only for the US Market.

Performance

For the year my stock portfolio was up 25% compared to 29% for the S&P 500. If I included the selling of stock to fund the I Bond purchases my total returns were 30%.

YearMeSPYDifference
202021.30%18.37%2.93%
202125.21%28.79%-3.58%

Where We Are Now

Below is an excerpt from “Buffett: The Making of an American Capitalist” by Roger Lowenstein.

Oddly, when Warren Buffett graduated, in 1951, both Graham and his father advised him not to go into stocks. Each had the post-Depression mentality of fearing a second visitation. Graham pointed out that the Dow had traded below 200 at some point in every year, save for the present one. Why not postpone going to Wall Street until after the next crash, his heroes counseled, and meanwhile get a safe job with someone like Procter & Gamble?

It was awful advice — violating Graham’s tenet of not trying to forecast markets. The Dow, in fact, never went under 200 again. “I had about ten thousand bucks,” Buffett noted later. “If I’d taken their advice I’d probably still have about ten thousand bucks.”

As of December 30 the US stock market had a CAPE ratio of 40 and the Buffett Indicator is about 215%. These metrics indicate the American stock market is overpriced and possibly in bubble territory. When I see indicators showing a massive overvaluation my tendency is to go to cash and wait for the market to collapse.

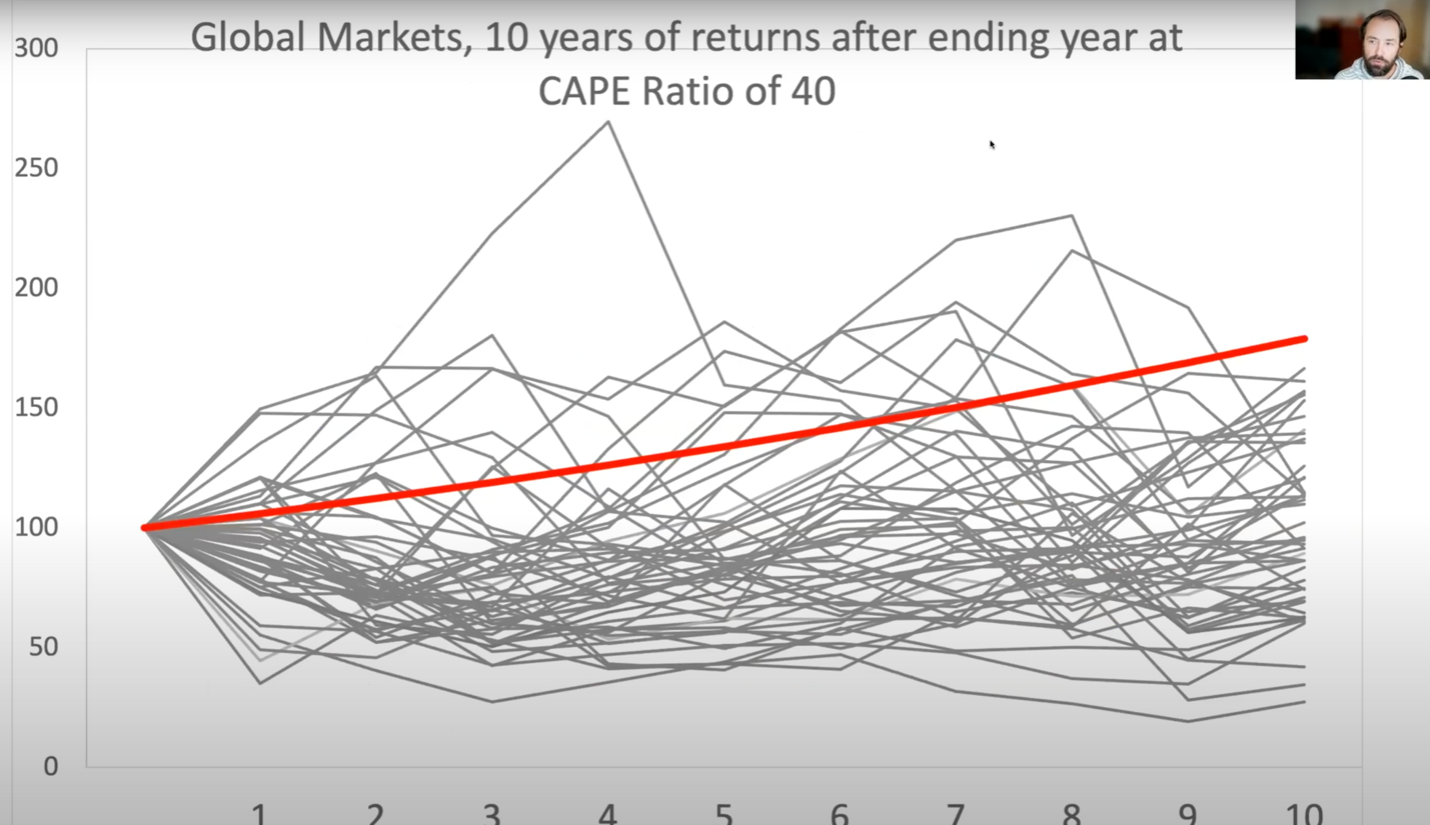
Meb Faber posted (image below) a chart of the returns of countries that traded at CAPE’s of over 40 (source: YouTube). The sample size is about 50 and the average real returns is 0%. The red line is a real 6% return per year and none of the countries, over ten years, were able to provide more than 6% return per year. Lastly, you’ll notice that most of the carnage (drawdowns) occur within the first three years.
It’s very possible the market is not overpriced. Fisher Investments argues that on a forward earnings basis the market isn’t a egregiously expensive. Bill Miller also doesn’t think the US stock market is that overpriced as a whole.

I used Buffett’s quote to remind myself that the stock market is one of the best ways to compound money and you shouldn’t be afraid of drawdowns. However, Buffett also said, “The less prudence with which others conduct their affairs, the greater the prudence with which we should conduct our own affairs.” Its that dichotomy of opinion that’s been weighing on me since my Q3 update.

One of Howard Marks’ mantra’s is to move forward, but with caution. I’m the type of person who focuses much more on what could go wrong than what could go right.

Based on my personal situation I’ve decided to slightly de-risk. Specifically, I took some gains off the table and allocated those funds to safer investments. Primarily, maxing out my contribution to I Bonds in January 2022. (I already maxed out my contribution in 2021.)

The primary reason to de-risk is I will have smaller amounts of additional capital coming in each month. The most important thing I can do is have enough capital to ensure I do not have to sell my investments in the event of a drawdown.

It’s extremely difficult right now to de-risk but it’s important to make these types of decisions when things are well and when I do not have emotional duress. A better way to say is by John Wooden, “When you fail to prepare, you’re preparing to fail.”

A little more detail about my personal finances; I have a home mortgage and about 65% of my monthly salary (including the HOA) goes towards the mortgage. With my cash balance, I Bonds and physical precious metals I have enough liquidity to pay my expenses for at least a year if I lost my job tomorrow. It could be argued I am being overly cautious but that’s why everyone should manage their finances based on their own risk threshold.

Lastly, having more cash means I can play fantasy baseball for higher buy-ins. In the past three seasons (2018-19 and 2021) I’ve played in six leagues and I’ve cashed in five of them (including winning three). At this point I believe my performance is not due to luck and warrants palying for more money.

I Bonds

(I first wrote about I Bonds in my 2021 Q2 Update.)

A friend of mine stayed with me over the Thanksgiving holiday. She got her Masters degree 12-16 months ago in physical therapy. She currently works at her local hospital, makes good money and will likely have the ability to be employed and make good money for as long she wants to work. She is very intelligent. If we took an IQ test her score would be at least ten points higher than mine.

To me, she represents the typical white collar worker in regards to the understanding of how compounding works in the stock market. Specifically, she understands the teachings of John Bogle.

  • That the base rate of the stock market over the past 80-90 years is roughly a 9-10% return per year.
  • The best way to accumulate to achieve that rate of return is via low-cost index funds.

Lastly, she has no interest in learning any more about investing, which is totally cool and understandable.

Since most of my free time is spent reading and thinking about finance some of our discussions were about finance.

I talked a lot about why she should look into putting money into inflation-linked savings bonds (I-bonds) because they’re currently yielding 7.12% and with inflation probably continuing to run hot for the next few months the interest rate will probably remain high when the interest rate changes in April 2022.

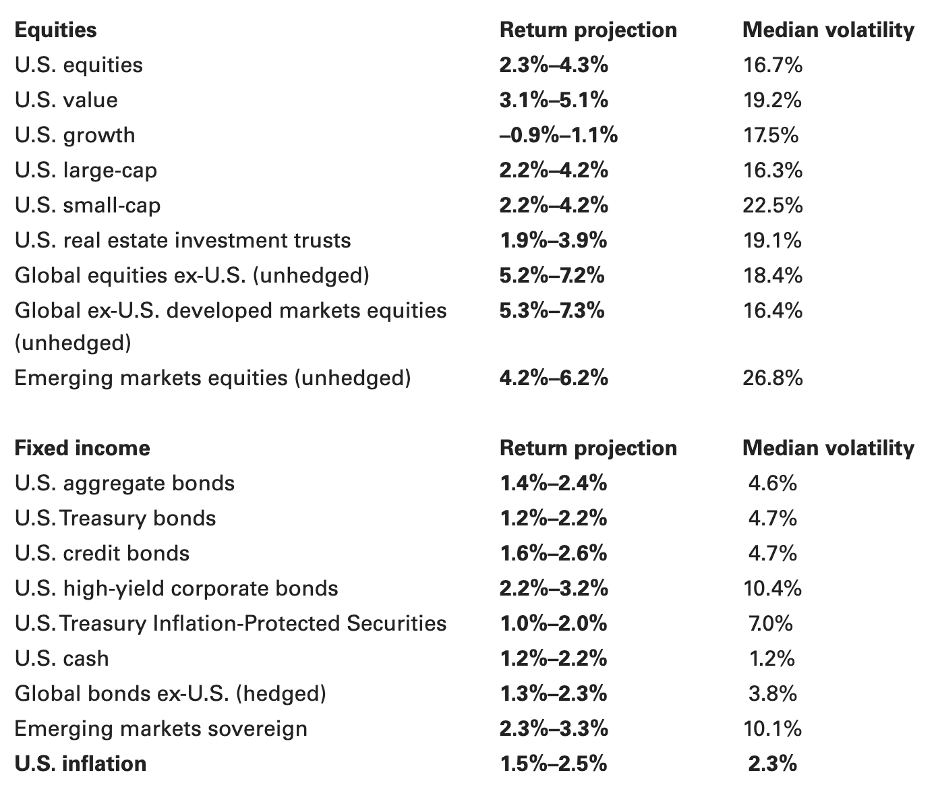
I told her I was pretty confident the I Bond would probably outperform a market cap weighted S&P 500 index fund in 2022 and possibly for the next five years. She asked, “why?” and I told her based on the two indicators I mentioned previously and at the current valuation the S&P 500 will maybe nominally yield 2-4% with dividends reinvested.

A week after Thanksgiving Vanguard came out with their forecasted 10 year nominal returns by asset class (below):
I think my friend’s hesitation to I Bonds was why should she buy a 7% yielding asset when the base rate of the US stock market is 9-10%?

Since March 2020 the market has essentially doubled and the economy has rebounded. What if she buys I Bonds and the market is up 18% next year? (“The S&P 500 has gained 5% to 10% just six times in the past 94 years. The S&P 500 goes up about two-thirds of the time, and when it does, it gains an average of 18%. It has declined about one-third of the time, with an average drop of 14%.” Source: Barrons.com)

I totally get it. No one likes to be wrong especially with hard earned savings…especially when you’re not in the minutiae of investing. I don’t know anything about cars and one of my friends knows everything about cars. If I had car trouble he could A) diagnose the problem quickly and B) would say it’s a quick fix; all I’d have to do is X. To him it’s a quick fix but for me it probably means I’m spending all of my Saturday trying to fix it. I imagine that’s how she feels when we were talking about finance.

The last thing I will say about I Bonds is if you qualify for a tax refund you can take payments in I Bonds. According to the IRS you can get up to $5k of your refund via I Bonds. To recap, you can buy up to $10k per year from the US Treasury and an additional $5k via your tax refund.

Portfolio Activity

I sold all my shares Alibaba and Tencent at a 11% profit to have additional money to pay for my 2022 contributions to my IRA and I Bonds. In my Q3 update I wasn’t expecting to sell those shares but as I mentioned above, my personal finances changed. I also sold all my Fairfax shares to buy more PLx Pharma and Micron.

Thoughts On Holdings

Briefly on Micron, about 70% of their revenue comes from DRAM. Micron now makes the industry’s smallest feature sized DRAM node which significantly outperforms the competition and at a lower cost. Micron also produced the first 176 layer NAND (this segment is about 25% of revenue) which is the most advanced NAND mode on the market. The biggest headwind for the company is China. When I first made an investment two years I thought it would be at least a decade before China had its own factories online. It appears China, with the help stealing intellectual property from Micron, may have their factories in a few years.

In mid-December the board of Equity Commonwealth approved an additional $150 million dollar buyback. With this additional $150 million authorized, the company now has $170.5 million available for future share repurchases, including $20.5 million remaining under its prior authorization that expires on June 30, 2022. As an owner of the business I am completely on-board with the board’s actions. The company has about $3 billion in cash and their market cap is $3.15 billion. This is a heads I win and I don’t lose very much if it comes tails.

In regards to Kinross Gold’s bid to buy Great Bear Resources, I’m okay with the deal. According to the press release 80% of the property hasn’t been explored yet and Great Bear has not released a resource estimate yet. This indicates there’s a bit of gamble in this purchase but I liked the management prior to the transaction and I’m going back their play.

In regards to The Acquirers ETF ($ZIG) it was recently announced the fund is not going to be shorting stocks in the future. With a current expense ratio of 0.89% I am going to reevaluate this holding in Q1 of 2022. Value is extremely cheap and according to the recent blog (it’s more of a chart than a blog) from Cliff Asness this may be the best time to be invested in Value so perhaps the expense ratio could be offset by the funds outperformance. In my 401k I’m 100% invested in a small cap value fund and the expense is 1.07% (it’s up 23.4% for 2021, which is a little less than the S&P 500) but since my investment options were limited and in my opinion, the value fund provided the most upside I choose the fund despite the costs. However, in my personal account I have vastly more options so the 0.89% expense may be too high.

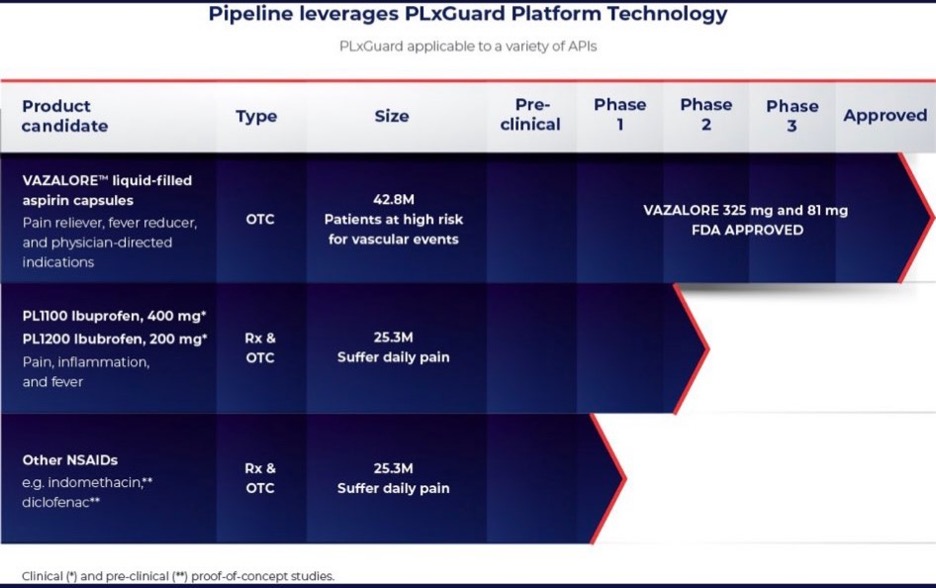
In regards to PLx Pharma, I haven’t sold any shares and I bought a little more. It’s been a strange two months for the growth stocks I track. Starting in mid-October companies like PLx Pharma and The Joint started their drawdowns from their all-time highs. I started buying the stock at $8 and I saw it rocket up to $20, never selling a share. In hindsight it would have made sense to sell a portion but for all I knew the stock could have been the next Gamestop or AMC. PLx Pharma has a market cap $219.2 million with $82.5 million in cash. The question is would I pay $133.7 million for an FDA approved medication that is substantially better than all the competitiors? Also, I’m getting 58 patents and the company is in clinical trials for different medications with the same delivery system as Vazalore. One headwind is pricing power. If we get a recession and/or inflation stays hot, will people want to pay more for the drug? In my mind, it’s an easy yes but the actions of people confound me every day.
“Having lost ground during the pandemic, military stocks are now at their cheapest valuations in eight years” (source: WSJ.com). I bought a basket of military stocks last year and I think these companies are extremely cheap especially since the government, no matter whose in power, continues to increase military spending. “The House voted Tuesday to approve a $778 billion defense-policy and budget bill that authorizes $25 billion more in defense spending than requested by President Biden” (source: WSJ.com).

Precious metals

I don’t have a predicitive or precise model on how to value any precious metal. The method I use is I divide the price of 1 ounce by the average home value. In other words, how many ounces of gold does it take to buy a house? Using that metic I can see how valuable a precious metal has become.

Homes are similar to precious metals in that, unless someone does Airbnb, homes don’t provide cash flow but they appreciate in value. Gold and silver are fairly valued. However, platinum is extremely cheap; in fact it’s the cheapest its ever been. One caveat, I only have 53 years of data compared to 70 years for gold and silver.

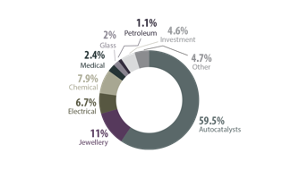
Even though platinum appears to be cheap there are some headwinds for the metal. Specifically the world is still over supplyed with platinum and its primary use is with autocatalysts in diesel engines (image source: Government of Canada). I’m not buying platinum at today’s price because I’m not smart enough to meaningfully know if platinum is really cheap at $980. However, if it gets below $800 I’ll be a buyer because at that price I think that’s a big enough margin of safety that doesn’t require expert knowledge to make a profit.
The table below is a breakdown of my portfolio on January 1, 2022. What you see below where my entire net worth, excluding my home, is allocated. Lastly, my 401k is 100% invested in a Small Cap Value Fund.

Company%
MU11.7%
BRK.B10.3%
PLXP6.6%
MKL6.2%
BAC5.7%
SCHW3.5%
MO3.2%
MMP3.0%
GVAL2.1%
AIMFF2.0%
EPD2.0%
ZIG1.8%
GLRE1.7%
HII1.7%
EQC1.6%
NEM1.5%
OGZPY1.5%
GD1.5%
NOC1.4%
KGC1.1%
ERUS1.0%
LMT1.0%
XOM0.9%
SMIT0.9%
CVX0.8%
PREKF0.5%
FNDC0.4%
EPOL0.4%
EWUS0.1%
LAND0.0%
FPI0.0%
ACGBY0.0%
Gold2.8%
Platinum0.7%
Farmland3.7%
I Bonds6.0%
Cash6.1%
401k4.6%

Below is a breakdown by category:

Bonds6.0%
Cash6.1%
Conglomerate10.3%
Defense5.6%
Financials9.2%
Insurance6.2%
International4.1%
Manager6.5%
Oil/Gas8.6%
Other3.2%
Pharma6.6%
Precious Metals6.1%
Real Estate5.3%
Semiconductor11.7%
Small Value4.6%
Posted in Investing | Leave a comment

Q3 Update: Strong Opinions, Weakly Held

Nothing discussed/written should be considered as investment advice. Please do your own research or speak to a financial advisor before putting a dime of your money into these crazy markets. In other words, if you buy something I bought, you deserve to lose your money.

The only reason why I am making my portfolio public because it provides accountability to me. Some or all the analysis I provide could be from the top of my head and should not be considered accurate.

My investing goal is simple; to try to manage risk while being fully invested without market timing. Howard Marks said it best, “even though we can’t predict, we can prepare.”

All my references to the Market are only for the US Market.

Performance

From Q2 to Q3 I am down 2% (SPY was up 2.3%).

YearMeSPY
202021.30%18.37%
202127.50%16.40%

Where We Are Now

The best movie I’ve seen this year is Empty Man (its free for HBO Max subscribers). In the beginning four hikers have to cross rickety bridge in order to continue their hike. That’s how I feel the markets are now. In other words, in order to have enough money for retirement or financial independence I have to cross this rickety bridge.

What’s different between October 2021 and March of 2020 is the condition of the bridge. In March the bridge was sturdy because I was buying Berkshire, Markel, Carriage Services, Schwab and Micron at extremely favorable prices. When Meb Faber, Jeremy Grantham, Tobias Carlisle, Jess Felder, John Hussman, Michael Burry and other OG’s say the Market is overheated it’s difficult not sell a lot of my gains and have a higher position than I currently have (its currently 3.1%).

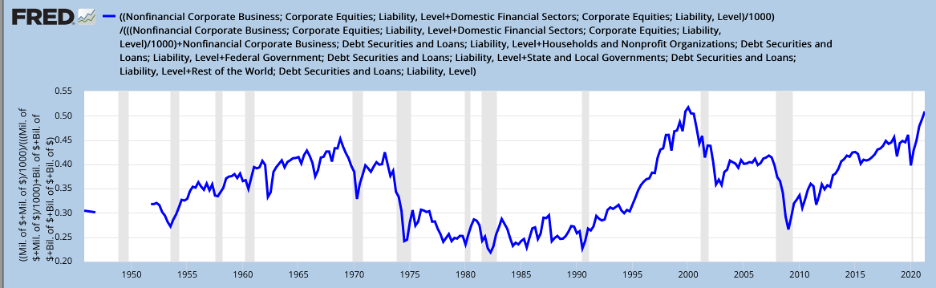
I recently came across this blog post by Jesse Livermore. He argues that percentage of stocks in all of investors portfolios is the greatest predictor of how hot the Market is. You can view the chart below (via FRED).

I absolutely love his article. Bubbles aren’t born with people calculating their rate of return or considering their risk tolerance; bubbles are born out of speculation. People see people making a lot of money and they want to jump in. When too many people are speculating the Market becomes a game of musical chairs because eventually there are less people willing to buy and hold stocks.

The FRED chart shows we’re almost at the peak of 2000. I can see a scenario where we’re at/near the peak of the bubble and the Market crashes like it did in the early 2000s. I can also see the continuation of a grinding, low growing bull market that we’ve experienced since 2009.

The average PE multiple for the past 31 years is 22.6 (excluding 2009). We’re currently at about 34, which is about one and half standard deviations from the mean. Using this information alone you can come to the conclusion that the Market is not in a bubble; it’s overheated but not a bubble.

There are two ways to interrupt what I’ve written so far. One is this is a typical late cycle talking point that is said right before the Market blows up. The other is the grinding bull market thesis is directionally correct; we’ll have corrections/minor speed bumps going forward but the Market grind upward. Whatever scenario occurs people will say they always knew which interpretation was correct in hindsight.

I currently believe we’re going to have a continuation of the grinding bull market. Ken Fisher has said for Market collapse to occur something really big that isn’t pre-priced in the Market has to happen. Inflation is top of mind in the financial media. My question is 3-5% inflation already pre-priced because the Market is constantly pre-pricing known information. Also, if you think a collapse is going to occur you have to assume the Federal Reserve and its printing press will not intervene. The Federal Reserve bought bond ETFs in 2020, which at the time was unheard of. What makes you think they won’t do something unheard during the next recession?

This is how I feel about my portfolio. I tried to implement a barbell approach to my portfolio. I think a valid criticism is I lean too much on the defensive side. Like most people I don’t like risk so the fact I haven’t trimmed my biggest position, which on paper right now, is a money losing company indicates I’m willing to let this position run.

I think my portfolio is relatively diversified (Chris Cole would probably say otherwise but that said, I am fan of the Dragon Portfolio. His work is the reason why I hold physical precious metals and bought farmland). What portfolio lacks is trend following. I think whatever new money I add to my account I should incorporate trend following.

This is how I’m managing my cash. I’ll make my annual contribution to my IRA next year but I am not planning to add any more money to the Market this year or next year. Other than my house I have no debt and my mortgage rate is 2.50%. I am going to hold more cash going forward for two purposes.

  1. My car, which is paid off, is relatively old and I want to have cash available for a new used car
  2. If I find a security that is a screaming buy I’ll have the cash to make a purchase

In other words, I have my opinion but its weakly held.

Portfolio Update/Activity

I sold all my shares Brighthouse Financial to buy shares in Alibaba and Tencent. I’m currently evaluating a potential third Chinese company. In regards to China as a whole, I think investors are too worried about China’s control on the economy and their corporations within it. I don’t have a massive amount of confidence in my China opinion but the prices I paid makes the best worthwhile and the bets are so small I can live with those investments going to zero.

I’m giving all my Chinese investments at least a year before I think about pressing the sell button. I honestly wanted to say two years instead of one, but if the stocks revert back to where they were a few months ago it would be difficult for me to not sell or trim the positions.

The table below is a breakdown of my portfolio on September 30, 2021 after the close. What you see below where my entire net worth, excluding my home, is allocated. Lastly, my 401k is 100% invested in a Small Cap Value Fund.

Company%
PLXP12.4%
BRK.B9.9%
MU8.9%
MKL6.4%
BAC5.9%
SCHW3.3%
MO3.2%
MMP3.1%
GVAL2.2%
EPD2.1%
AIMFF2.1%
HII1.8%
OGZPY1.8%
ZIG1.7%
GLRE1.7%
EQC1.6%
BABA1.5%
GD1.4%
NOC1.4%
NEM1.4%
ERUS1.2%
KGC1.1%
XOM0.9%
LMT0.9%
SMIT0.8%
TCEHY0.8%
PREKF0.8%
CVX0.7%
EPOL0.5%
FNDC0.4%
RTX0.4%
FRFHF0.4%
FFXXF0.2%
EWUS0.1%
FPI0.0%
LAND0.0%
ACGBY0.0%
SRMLF0.0%
Gold2.8%
Platinum0.7%
Farmland3.8%
I Bonds3.6%
Cash3.0%
401k3.3%

Below is a breakdown by category:

Bonds3.6%
Cash3.0%
Conglomerate9.9%
Defense5.9%
Financials9.1%
Insurance6.8%
International7.0%
Manager6.3%
Oil/Gas9.4%
Other3.2%
Pharma12.4%
Precious Metals5.9%
Real Estate5.5%
Semiconductor8.9%
Small Value3.3%
Posted in Investing, Uncategorized | Leave a comment

2021 NFBC 12-Team Mixed League Recap

The 2021 season ended and I finished in second place; the standings can be found in the image below. Obviously I didn’t get the outcome I hoped for but I doubled my money. To see my thoughts right after the draft please see my 2021 draft recap.

In my last five leagues (all NFBC 12-team mixed league 5×5 roto) I’ve finished in the money in all of them and won three of them. The main reason for my success has been finding value that is undervalued by the Market. I’m going to discuss are some of my biggest draft successes and failures because I believe that’s the only way to consistently improve.

*all ADP data is from NFBC and Player Rater data is from ESPN. Also you’ll see my preseason projections and their 2021 output.

Successes

Tommy Edman: He had an average ADP of 127. I selected him 98th overall. He finished the year as the 33rd most valuable player on the Player Rater.

 ABAVGHRRBIRSB
Projection550.283176510018
2021641.26211569130

I didn’t think he would steal that many bases, but when you draft a player who can steal 15 or more bases you’re basically buying a call option on the player wildly surpassing your expectations. After looking at his advanced stats this year I was too optimistic on the home runs. I think I will project 10-13 home runs for him next season.

Will Smith: I didn’t draft him but on May 16 I acquired him via waivers for a $271 of my FAAB. The next highest bid was $108. I have no idea why he was dropped and no one wanted him. When he was dropped he was hitting approximately .230/.380/.452 with three home runs. However, if his fantasy owner, who actually finished 11th out of 12 teams, actually looked at the advanced stats he/she would’ve known Smith was a far better player than his small sample suggested. Smith finished the year as the 3rd best catcher on the Player Rater.

 ABAVGHRRBIRSB
Projection420.2671868600.5
2021414.2582576713

Next year Smith will either be my 2nd or 3rd catcher because he hits high in the lineup and will get more RBI and R opportunities. If the NL gets the DH I may give the edge to Realmuto because I think the Phillies will give him 20 games at the DH while I think the Dodgers will give the DH to other hitters.

Eduardo Escobar: I drafted Escobar (290th overall) as an insurance policy for my CI positions. He finished the year as the 85th best player overall on the Rater.

 ABAVGHRRBIRSB
Projection570.26423.585772
2021549.2532890771

After my draft I wrote, “Escobar is always underrated. He’s going to hit fourth in the lineup and hit 20-25 home runs with a lot of RBI and a batting average that won’t hurt you.” I think the Market saw his brutal 2020 numbers and thought he was done. He may have been but the price I paid meant my downside was protected. 

Mitch Haniger – I drafted Haniger and Polanco (below) back-to-back in my draft (191st and 194th overall respectively). I didn’t see the power coming from Haniger but I knew he was probably their best or second best hitter and he was going to hit high in the lineup if he was healthy. The biggest reason why he was so heavily discounted was he didn’t play baseball for 1.5 years. But when he was healthy he was a very good hitter. Like I mentioned several times already; at the price I was paying I didn’t have much downside.

 ABAVGHRRBIRSB
Projection520.27022.570865.5
2021620.253391101001

I don’t think the power is legit and he’ll probably be overdrafted next year. I’m going to project 26-29 home runs next year with a .249 batting average. The contact rates are declining and he’s not going to steal bases anymore. Also, he’s probably going to bat 4th which means he won’t score as many runs.

Jorge Polanco – Polanco was unfairly punished in drafts for reasons unknown. If I were to guess it was due to his subpar 2020 shortened season. Quick aside; I have no idea why anyone heavily weighted the 2020 season. It was 50-60 games. So much randomness can occur in that amount of time.

 ABAVGHRRBIRSB
Projection580.2832085856.5
2021588.26933989711

Among shortstops Polanco was rated 12th; the Market rated him 24th. Finding players that are underrated by the Market is how you win leagues. If you pay market price for everyone you’re going to have an average team. The Market hated Polanco so much he went after Willi Castro. Polanco’s power is not legit; I think he’s a 20-25 home run guy with a .267 batting average next year. He’s going to hit in the top four spots of the lineup next year and he should accumulate similar stats as last season.

Anthony DeSclafani: I didn’t have a lot of pitching success this year which is why there’s only one pitcher mentioned. It seems like DeSclafani is always on my teams. I think he’s always underperformed his true talent which is why I always think he’s a value in drafts.

 InningsERAWHIPKW
Projection1703.751.2017510
2021167.23.171.0915213

I thought the Giants would be very bad this season which is why I underrated his win projection. DeSclafani got very lucky during his road starts; he had 4.02 xFIP compared to a 3.22 ERA. He’ll be a free agent after the playoffs so his value will be dependent on where he lands. Since he had a good baseball card statistics he may be overdrafted next year.

Sal Perez: I had Perez as my second catcher overall and I had zero expectations he would have the season he’d have. The most shocking statistic was games played and his at-bats. The Royals played him at DH for 40 games.

 ABAVGHRRBIRSB
Projection470.26024.580620
2021620.27348121881

Considering the Royals don’t have a deep lineup I hope the Royals play him more at DH. That said, the power looks like an outlier; kind of like Pete Alonso’s rookie season. I think Perez will hit 30-35 home runs with a .260 batting average. If you look at the big decline in contact rates it’s very possible he only hits .250 next year. If you’re in a 12-team 2-catcher league is Perez a top 20 hitter? I think he may be but if you pay that price he has to hit .260 with 30 home runs and get 580 at-bats. For me, the price may be too high but that may be his fair value.

Failures

Charlie Blackmon: I didn’t have high expectations for Blackmon as evidenced by projection below. The biggest reason why I liked Blackmon was the batting average he would have provided and I didn’t see any decline in his advanced metrics.

 ABAVGHRRBIRSB
Projection570.2952493852.5
2021514.2701378763

As of now I think he was a little unlucky with the batting average but I think the days of him hitting above the .290’s are over. I think you can project a .280 batting average. I think there is more power in the bat. He had 3% HR/FB rate on the road. Maybe the new ball dampened his power potential but 3% is extremely unlucky. I’ll estimate 15-18 home runs next year.

Nick Senzel – I give myself a mulligan on Senzel because he didn’t play much. However, with Jonathan India cementing himself at second base the only position Senzel can get at-bats is in center field. When Senzel was healthy he was sharing center field with Tyler Naquin. If Senzel was highly regarded by the Reds he wouldn’t have had to split time a fourth outfielder in Naquin.

Zack Greinke – I drafted Greinke in the 12th round and as the 60th starting pitcher overall. I thought after my draft I got a steal. There was downside with Greinke but at the price I paid I thought it was worth the risk. Also, I didn’t think he would decline as much he did.

 InningsERAWHIPKW
Projection1903.551.1217013
20211714.161.1712011

If Greinke wants to play next year he’ll find a team like the A’s, Pirates, or Rays that will give him a cheap one year contract but at this point he’s no more than the 6th starting pitcher in a 12-team mixed league because the low strikeouts totals will hamper your team.

Pitching In General – I got too cute with my starting pitching. I built my strategy on mixing and matching all year long but injuries and Covid forced me to have more hitters on my bench which meant I had to start pitchers I didn’t want to all the time. I think next year I’ll have to pay for pitching earlier in my drafts.

Posted in Fantasy Baseball | Leave a comment