Q2 Update: Fully Invested Bear

Nothing discussed/written should be considered as investment advice. Please do your own research or speak to a financial advisor before putting a dime of your money into these crazy markets. In other words, if you buy something I bought, you deserve to lose your money.

Even though no one will read this I am making my portfolio public because it provides accountability. Some or all the analysis I provide could be from the top of my head and should not be considered 100% accurate.

For the second quarter I’m up 17.9% while SPY, a S&P 500 index fund, is up 5.9%. I honestly don’t care what my performance is quarter to quarter because there is nothing intelligent that one can say about short periods like three months.

All my references to the Market are only for the US Market.

My goal is simple; to try to manage risk while being fully invested without market timing. Howard Marks said it best, “even though we can’t predict, we can prepare.”

*this letter may not be as well written as previous letters; that is because I was in the middle of a move.

Portfolio Update

For the year-to-date I am up 27.3% while the S&P 500 is up 15.3%. My outperformance this quarter was due to value stocks continuing to do well and PLx Pharma Inc. increasing 62%. I have been adding to the position and it is now my third largest holding on a cost basis.

Where We Are Now
Inflation has been running hot but the bond market doesn’t care. In fact, US bond yields have been decreasing in June. On March 29, 2021 the 10-year Treasury closed at 1.721%. At the close on June 30 it closed at 1.485%. Adam Robinson says when the Market is doing something and you’re confused by what’s happening the onus is on you to update your view of the world.

A lot of legendary investors say the bond market is the most intelligent of all the equity markets. I know the Federal Reserve is buying a lot of bonds, but they can’t be buying all the bonds and thus, causing the interest rates to decrease.

So, what is the bond market telling us? My best guess is they think inflation is indeed transitory and/or GDP growth is going to slow down a lot; possible as soon as the end of 2021. If growth slows then US stocks are going to take a dive especially the little to no revenue growth names.

However, it’s possible low bond yields are near term bullish for stocks. “The S&P 500 closed at a new all-time high this past week (June 11, 2021), while the 10-year yield closed at its lowest level in three months—only the 18th time since 1968 that the index closed at a three-year high while bonds traded at a near-term low. On previous occasions, the S&P 500 was higher six months later 82% of the time, with a median gain of 6.9%. Growth stocks gained 5.4% and were higher 71% of the time, while value stocks gained 11.2% and were higher 88% of the time—giving value the upper hand.” (Source: Barrons.com)

Lower interest rates are good for stocks but I keep coming back to:

  • Can the Federal Reserve keep buying assets forever?
    • No. When will they stop? No one knows especially since they’re the ones with the money printer.
  • Stocks can’t go up forever.
    • In the fabulous book Bull! By Maggie Mahar there were professional investors who called a top in 1995 and they had to wait five years before deploying their capital. Am I capable of selling and going to cash?
  • As a world, especially in the developed parts, growth in GDP is going to be difficult because of demographics.
    • If you combine a low growth world with a ton of debt and already all-time low interest rates things don’t look good. In that world having cash maybe more preferable.
  • If I sell stocks and go to cash I am trading in an asset like Bank of America that will give me a shareholder yield of about 7-10% for an asset that will lose its value over time. On the flip side, having cash is like having a huge call option.

“The periodic liquidation of parts of a portfolio has a cathartic effect. For the many investors who prefer to remain fully invested at all times, it is easy to become complacent, sinking or swimming with current holdings. ‘Dead wood’ can accumulate and be neglected while losses build. By contrast, when the securities in a portfolio frequently turn into cash, the investor is constantly challenged to put that cash to work, seeking out the best values available.” (Source: Margin of Safety by Seth Klarman)

I’m very uneasy about the forward returns for US market. I’ve seen forecasts as low as negative five percent to maybe four percent after inflation with dividends reinvested.

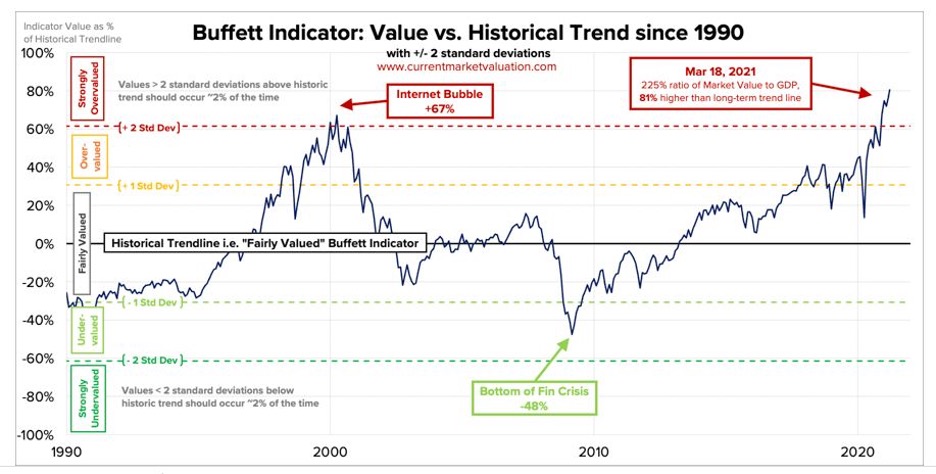
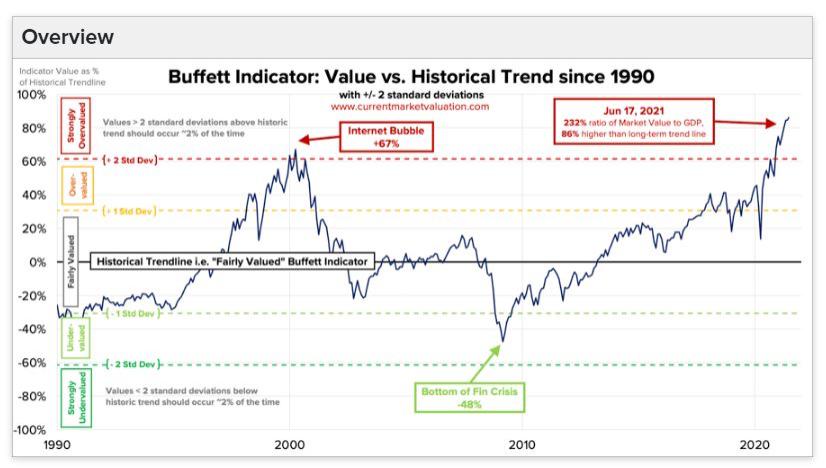
As of now I’m a fully invested bear. When I see the Buffet Indicator and Cape Ratio at screaming high levels it’s extremely difficult to not have any cash lying around because I wouldn’t be surprised if at any moment US stocks get a correction larger than 10%.

Most importantly, do not confuse a bull market for intelligence.

Inflation

In my Q1 update I cited the increase in bank loans as a catalyst for inflation. Well, according to the latest data loan volume is almost back to levels seen in January 2020. I have no feel for what will happen with inflation; I can see either scenario playing out and I won’t be surprised at either outcome.

Bonds

I Bonds

Since I’m a homeowner again it’s important to build up my rainy day fund. Most people need 3-12 months of costs saved. How many months is the best? It’s a personal choice. Having a lot of cash with interest rates at 0.5% and 2-5% inflation is an awful prospect.

I read the articles from the Rational Walk and Jason Zweig about I Bonds. They currently yield 3.54% until Nov. 1, 2021. The interest rate resets every six months and interest is earned on the bond every month.

Quoting from Mr. Zweig’s article, “What if interest rates or inflation head lower? Yes, the yield can decline. But, unlike with Treasury inflation-protected securities, or TIPS, the yield on I bonds can never go below zero.”

You can buy up to $10,000 a year. I Bonds are also exempt from state and local income tax but they are subject to federal income tax. If you hold for five years or more you get the full amount of interest. If you sell them between 1-5 years you lose the previous three months of interest. You have to hold the bonds for at least 12 months.

Inflation for May was five percent. Buying a bond that only yields 3.54% doesn’t make sense. However, a rainy day fund is emergency cash so in my opinion you should consider what interest rates can you get for your cash. I can’t find anything larger than 3.54%.

Most importantly (for me), the real interest rate on my home is 2.70%. If I can put money into I Bonds at 3.54% I should make a slight profit on the spread (between the two rates) even after paying Federal taxes.

In other words, I believe I Bonds are fantastic for my personal situation because after five years I could cash out my I Bonds and pay my mortgage and make a slight profit with virtually zero risk.

Portfolio Activity

I added a starter position to PrairieSky Royalty ($PREKF) in my IRA. I had to buy it in my IRA because of the way the dividends are taxed. They’re a passive foreign investment company (“PFIC”), which is a fancy way of saying you’ll get taxed a ton. Since Micron was a big part of the IRA I had to trim it; I didn’t want to pay exhorbant amount of taxes. (I am still very bullish on Micron.)

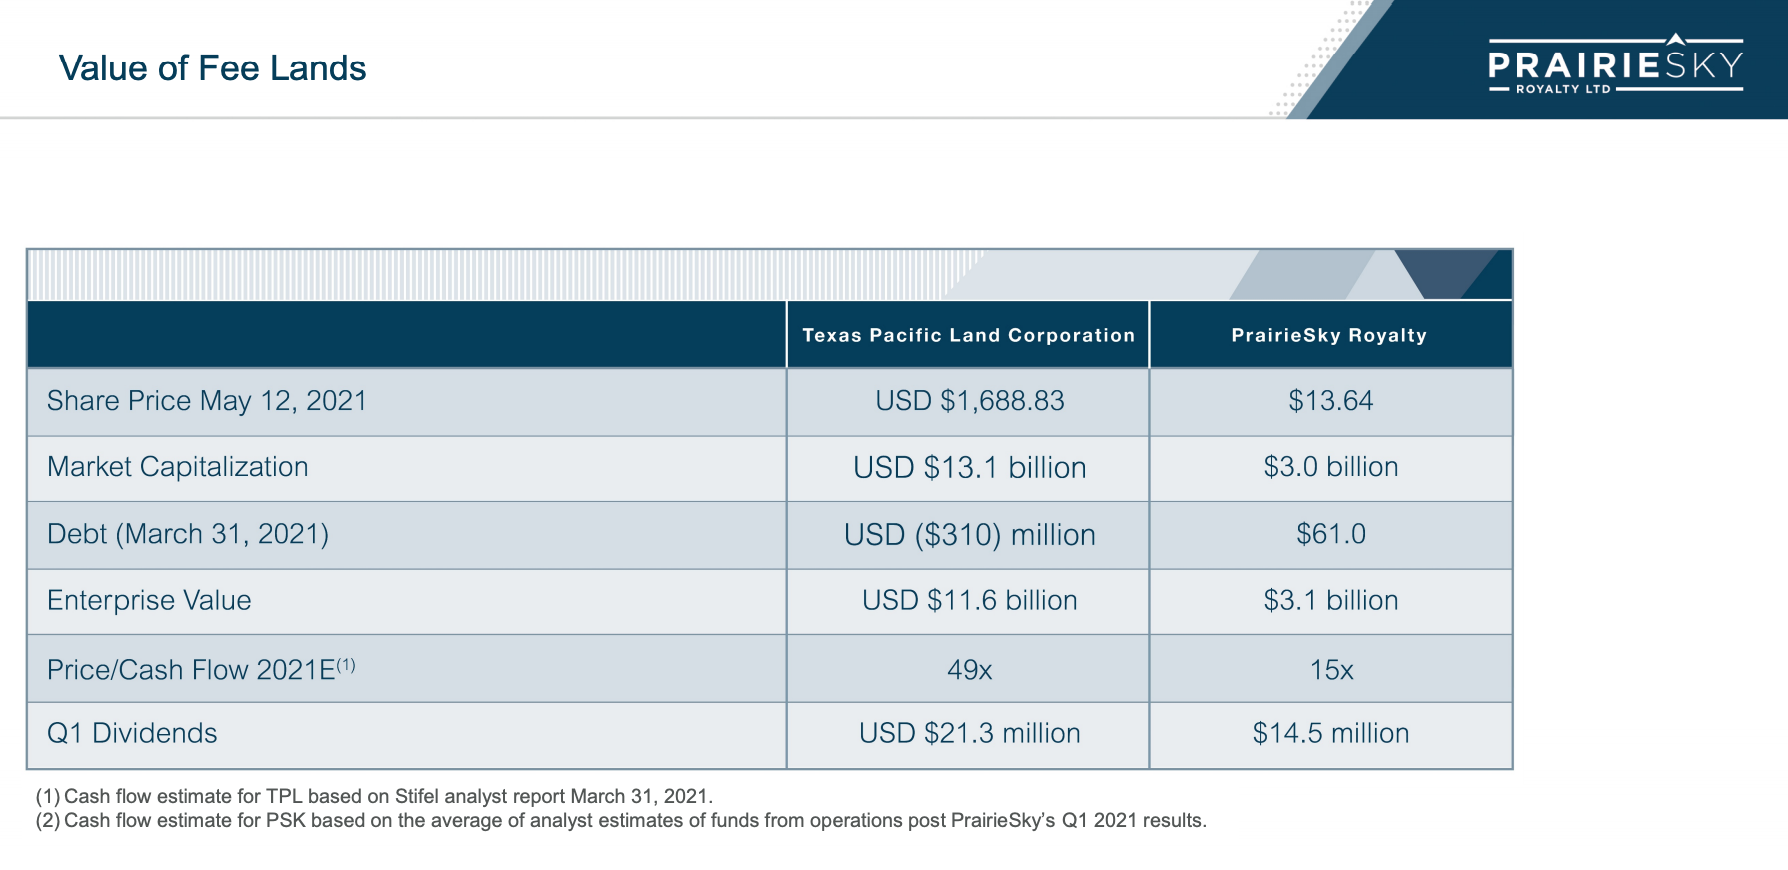
PrairieSky is a pure-play royalty company, generating royalty revenues from oil and natural gas across 16 million acres in Western Canada. I came across them because the business model was very similar to Texas Pacific Land Corporation ($TPL).

PrairieSky has a large buyback (they bought 4% of shares last year), virtually no debt and is selling at a much lower multiple than $TPL (image below and source of image). I approximate a free cash flow yield at 6% without a lot of costs to run the business.
I bought Schmitt Industries ($SMIT) at two-times book value. They company is based in Portland, OR. In fact, their office is a two minute drive from one of my hiking spots in Forest Park.

Schmitt designs, manufactures and sells high precision test and measurement products, solutions and services via their Acuity and Xact product lines.

The Acuity product uses laser measurement sensors for dimensional measurement in a wide range of applications, including factory automation, surface profile scanning, crane positioning, road profiling, tire production, semiconductor manufacturing and many other industrial and commercial applications.

The Xact product uses satellite remote tank monitors include both ultrasonic and gauge reader sensors that provide remote fill level monitoring of propane, diesel and other tank-based liquids for tanks anywhere in the world.

Another very attractive aspect to Schmitt is they have a combined NOL for about $11-12 million at both the federal and state level, which could be used to offset future taxable income or otherwise payable taxes.

I’m most intrigued by the CEO Michael Zapata. I saw he was mentioned in William Green’s new book Richer, Wiser, Happier. I also listened to an interview with him on Invest Like The Best Podcast. Based on my research Mr. Zapata seems like an incredibly intelligent investor. In July 2020 Schmitt bought Ample Hills Creamery for an incredibly low price. He currently owns about 14-15% of the stock. Having an owner-operator is a double edged sword; things go really well and very poorly.

In Guy Spier’s book The Education of a Value Investor he discusses how by owning shares in a company you’re now in a relationship with management. From everything I’ve read I want to be in a relationship with Mr. Zapata.

The table below is a breakdown of my portfolio on June 30, 2021 after the close.

Company%
MU12.6%
BRK.B10.7%
PLXP9.6%
MKL6.7%
BAC5.9%
MMP3.6%
MO3.5%
SCHW3.4%
AIMFF2.3%
GVAL2.3%
EPD2.3%
GLRE2.2%
HII2.1%
EQC1.8%
ZIG1.8%
NEM1.7%
NOC1.5%
GD1.5%
OGZPY1.4%
KGC1.4%
EWY1.2%
ERUS1.2%
SMIT1.1%
LMT1.0%
XOM1.0%
BHF0.9%
PREKF0.9%
CVX0.7%
FNDC0.5%
EPOL0.5%
EWS0.4%
FRFHF0.4%
RTX0.4%
FFXXF0.3%
ICOL0.2%
EWUS0.1%
FPI0.0%
LAND0.0%
Cash0.8%
Gold3.0%
Platinum0.8%
Farmland4.1%
I Bonds2.1%

Below is a breakdown by category:

Bonds2.1%
Cash0.8%
Conglomerate10.7%
Defense6.5%
Financials10.2%
Insurance7.1%
International6.7%
Manager7.4%
Oil9.8%
Other3.5%
Pharma9.6%
Precious Metals6.9%
Real Estate6.0%
Semiconductor12.6%
Grand Total100.0%
Posted in Investing | Leave a comment

Q1 2021 Update

Nothing discussed/written should be considered as investment advice. Please do your own research or speak to a financial advisor before putting a dime of your money into these crazy markets. In other words, if you buy something I bought, you deserve to lose your money.

Even though no one will read this I am making my portfolio public because it provides accountability. Some or all the analysis I provide could be from the top of my head and should not be considered 100% accurate.

For the first quarter I’m up 17.9% while SPY, a S&P 500 index fund, is up 5.9%. I honestly don’t care what my performance is quarter to quarter because there is nothing intelligent that one can say about short periods like three months.

All my references to the Market are only for the US Market.

My goal is simple; to try to manage risk while being fully invested without market timing. Howard Marks said it best, “even though we can’t predict, we should prepare.”

Where We Are Now

I have no idea what the Market will do in the future. All I can do is try to understand where we are. This is where I think we are:

  • The Market is expensive. The S&P 500 is trading at 20 times forward earnings which is the 90th percentile of its valuation for the past 30 years.
  • A lot of forward returns have been pulled forward to today, which means future returns will probably be low; a Bank of America analyst thinks the S&P 500 will only return two percent per year the next ten years; if you add two percent in dividends that’s only four percent per year.
  • The Market is in a bubble (image below and links to other images here and here) but there are still of areas of the Market that are still cheap. More on this in the next paragraph.
  • Interest rates are extremely low but I do not believe interest rates is the reason why the Market is expensive. For example, in 1999 the 10 year treasury was yielding 5-6% and the Market got even more insanely priced.

There is a bubble in SPACs, revenue losing companies, NFTs, meme stocks, penny stocks and some parts of the tech sector. However, I do not believe the Market as a whole is in a bubble. For example, Newmont is selling at 13.5 forward P/E; Bank of America at 14 forward P/E; Berkshire Hathaway is trading at 1.3 times book value. All these companies are selling at reasonable prices. If the Market was in a bubble these companies wouldn’t be this cheap.

Positioning for 2021

I’m fully invested. Most of my portfolio is in value, which accomplishes two things.

  1. Value is very cheap. Buying companies at reasonable prices protects me on the downside in a bear market and provides more upside in a bull market.
  2. Value will benefit from inflation. I came into 2021 thinking heavily about inflation and I attempted to position my portfolio to do well in an inflationary environment. I discuss more about inflation in the next section.

There are many scenarios that could happen to the Market. One is the Market is basically sideways for the next 1-30 months. In sideways Markets you want to own dividend paying stocks. John Bogle calculated that during the 81 years to 2007, reinvested dividend income accounted for approximately 95% of the compound long-term return earned by the companies in the S&P 500.

Another scenario is the Market continues to go up like it did in the late 1990s. Very smart people were saying in 1996 we were in a bubble and it took four years for the bubble to pop.

I do not believe we are in a bubble but if I did believe we were in a bubble I would not want to hold cash because:

  1. I have no idea how long this bull market will last
  2. With all the money printing I don’t want my cash to be inflated away
  3. I do not have the mental fortitude to be in cash for a year or more

Quick hypothetical: If my portfolio had a million dollars I would only be 50% invested. I say that because when the bull market ends, it’s going to end badly and I would want to have cash ready to deploy.

Inflation

I have no idea if we’ll get a spike in inflation this year or next year. There are many possible scenarios for inflation and deflation to occur.

One scenario is we get inflation but in a way that isn’t measured by the Federal Reserve.  For example, their inflation gauge/metric they use does not include the price of home real estate, college education and health care. I think most Americans have experienced one form of this inflation. But since the Fed Reserve does not incorporate those metrics, they can continue to lie to the American people and say inflation has been below three percent the past ten years.

Another scenario is we get inflation for a few months then we go back to deflation. The Federal Reserve said it’s going to keep short term rates at 0% until 2023. Japan during the last ten years have shown that low interest rates creates deflation. When retirees have no yield on their savings they have to save more and therefore, spend less.

 A third scenario is we get stagflation. This scenario would be extremely bad for society if this occurred. If this occurs, it will take several years for this to happen.

A fourth scenario is we continue to have inflation be under two percent.

I have hard time believing we do not get inflation when A) governments in the developed world, except China, are printing a lot of money and devaluing their currency and B) government’s (America, UK and Europe) are providing credit guarantees to the commercial banking system. In the last 10-11 years banks didn’t make loans due to regulatory constraints. In other words, new money is going to be pumped into the economy via loans from banks.

It’s very possible why America has had low inflation the past the ten years is because all the money that was printed went into equities and asset prices and the money stayed out of the economy. The profits for the S&P 500 peaked in 2016. What has caused the Market to increase so much since 2016 is multiple expansion (investors paying more each dollar in profit). But now, with banks pumping money into the economy I think the odds of meaningful inflation have increased.

The future is unknowable. The best I can do is construct a portfolio that can do well in a variety of environments. If inflation doesn’t occur I should do well because of mean reversion; or in other words, the companies I bought at low prices will positively revert. If we get inflation my exposure to gold, precious metals, miners, oil, pipelines, farmland and real estate should do extremely well.

Quick aside: The most maddening part of all the money printing in America is it probably means we will no longer be the world’s reserve currency in about 10-15 years (to China), which means the people who bear the brunt of all the negative consequences are the kids under the age of 10. It saddens me that something like 65-70% of the elected officials in the three branches of government are over the age of 65. That means when the negative consequences occur A) they will all probably be dead and B) a lot of them are so rich already that their heirs will live comfortably.

Gold

Here are three facts about gold (source):

  • Gold and the Dow were both 800 in 1980. Today Gold is $1,700/ounce. The Dow is near 32k
  • Over the last twenty years, Gold is up 340%. Stocks are up 208%, with dividends
  • Since 1980, Gold is up 153%. Inflation is up 230%

About five percent of my portfolio is in physical gold. I own gold because I want an asset that is not part of the government’s monopolistic financial system. That rationale makes me sound like someone who has a bunker in his backyard but it is clearly obvious governments are devaluing their currencies so I want a hedge my exposure.

In 2012 government mandated, with the blessing of the Supreme Court, that all Americans have to pay for health insurance and if someone doesn’t you have to pay a tax. Never think the government has a limit on what they will make us do financially.

The table below is a breakdown of my portfolio on March 31, 2021 after the close.

Company%
MU15.3%
BRK.B11.2%
MKL7.3%
BAC6.3%
PLXP5.3%
MO4.3%
MMP3.5%
SCHW3.4%
AIMFF2.7%
GLRE2.5%
HII2.4%
EPD2.3%
EQC2.1%
ZIG1.9%
NEM1.8%
GD1.6%
KGC1.5%
NOC1.5%
OGZPY1.3%
LMT1.1%
XOM1.0%
BHF1.0%
FRFHF0.9%
CVX0.8%
DTLA0.7%
RTX0.4%
FFXXF0.3%
FPI0.0%
LAND0.0%
SMIT0.0%
  
ECH0.5%
ENOR0.0%
EPOL0.4%
ERUS1.4%
EWP0.0%
EWS0.5%
TUR0.4%
EWI0.0%
EWUS0.1%
GVAL2.4%
FNDC0.5%
EWY1.3%
FNDE0.0%
AVDV0.0%
ICOL0.3%
  
Gold (Physical)3.2%
Platinum (Physical)1.0%
Farmland3.5%

Below is a breakdown by category:

Row LabelsSum of %
Conglomerate11.2%
Defense7.0%
Financials10.6%
Insurance8.2%
International8.2%
Manager7.1%
Oil8.9%
Other4.3%
Pharma5.3%
Precious Metals7.6%
Real Estate6.4%
Semiconductor15.3%
Grand Total100.0%

Quick note: “Manager” is defined as I invested because of the person/people running the company/fud.

Portfolio Additions/Commentary:

PLx Pharma ($PLXP)- Thomas Phelps, in his book, 100 to 1 in the Stock Market said, “find new products that improve lives.” I believe PLx Pharma is one those products. Simply put, there has been no innovation for aspirin in 70-80 years. PLx Pharma recently had their second version of aspirin (VAZALORE) approved by the FDA.

They have two versions of VAZALORE; a 325mg and a 81mg version. The 325mg has been approved but there was a 2.5-year delay in the approval of the 81mg because of manufacturing issues.

VAZALORE is the first FDA approved liquid-filled aspirin capsule. VAZALORE is better for blood clotting and its better absorbed in the GI tract, which significantly reduces the risk of stomach erosion and ulcers. This is achieved by the unique delivery system of the capsule.

My brother has a PhD in organic chemistry and he backed up the science of the pill. I also provided information about VAZALORE to two actively practicing doctors (in different geographic locations) and they both thought VAZALORE could scale well.

Most importantly, the company has 58 patents across various countries (USA, China, Japan, Mexico, South Korea) that extends into 2032. Also, they have pending patents in Europe, Canada and India; if they’re accepted the patents will be valid through 2032.

In early March it was announced the 81mg was approved by the FDA. They are currently ramping up production and begin selling it to hospitals in the third quarter.

Overall, the board of directors owns about 10% of the stock. Half of the CEOs and the Executive Chairman’s stock options have an exercise price of $12.50 by 2025 so they are incentivized to do well. Also, members of the board and upper management have been buying the stock the past 6-12 months.

The total addressable market for aspirin in the USA is $9-11 billion. If they get 10% of the market they could have $1 billion in revenues which means they could have a market cap of $5-10 billion. When I started buying the market cap was about $175 million so we’re looking at a possible 400-500% return with room for a lot more.

Lastly, the delivery system of VAZALORE could also be used for ibuprofen (aspirin and ibuprofen can be used to treat the same pains but they are different drugs). The company is currently in one Phase 1 trials with the FDA.

Magellan Midstream Partners ($MMP)- I believe Magellan will provide a safe ten percent dividend. They will have minimal maintenance capital expenditures. I think America isn’t going to be building any new pipelines in the near future and possibly for my lifetime. Since no new capital will come into this industry, Magellan has a strong moat. Oil will continue to be used in meaningful way for at least another 20-30 years. The capital allocation of the management is good. They paid off 2020 debt which had a four percent yield by taking out a loan that’s due in 2024 at a three percent yield; they have no debt for the next four years. I bought the stock at around $40 so after four years I will have received $20 in dividends. As of today, I think the stock is worth about $80.

Altria ($MO)- I don’t care about the negative effects Altria’s products have on their customers. What’s difference between cigarettes and alcohol? I would argue alcohol has had a bigger negative impact on society than cigarettes. How about Coca Cola? McDonalds? All these companies produce products that slowly kill their customers too. Why do only cigarettes get the bad rap? When I bought Altria it was extremely cheap with a 10% earnings yield. Also, the company has pricing power that will do well inflationary periods.

Altria is an incredibly resilient company. If you look at their revenues even though consumption has decreased revenues have continued to grow. The government makes a ton of money from Altria via taxes, so the government is incentivized to leave Altria alone. Also, it is virtually impossible for a new company to come in because cigarette companies are not allowed to advertise which further entrenches Altria’s moat. Also, Altria owns a big share of Cronos, the Canadian cannabis company. If the Democrats legalize weed Altria will be able to utilize their distribution system to take a share from these smaller companies.

Equity Commonwealth ($EQC)- this is a bet on Sam Zell. I bought the stock at about $27. The company has no debt and has $24 dollars in cash. So basically, I’m getting about 85-87% of the cash and with all that cash I have Mr. Zell and his team allocating it. I think Mr. Zell and his team are better capital allocators than me. This is a heads I win a lot and a tails I don’t lose very much.

Greenlight Capital Re, Ltd. ($GLRE)- this is a bet on David Einhorn. He was probably one of the best investors in America in the 2000s but in the 2010s he has been very below average. I’ve read his book and his letters. I think he’s a better capital allocator and stock picker than me. Also, his stock portfolio will do very well in an inflationary period and most importantly, there are shorts, which means if the Market does have a big drawdown the portfolio will benefit. My buy price was about $7.75 which is about 58% of book value.

The Acquirers Fund ($ZIG)- like Greenlight Capital I am betting on A) the person running the portfolio (Tobias Carlisle), B) the portfolio is long Value and has shorts and C) the price point being cheap enough there isn’t that much downside. I’ve read all his books and I believe he’s a better capital allocator and stock picker than me. (Can you see a trend here?)

Like Greenlight, The Acquirers Fund is a long-short portfolio. I like the long-short portfolio because if there is severe downside to this Market the shorts will lessen the drawdown. Also, since bonds less than inflation the best thing to hedge downside risk is with a long-short portfolio.

I’m not a fan of the high fees of the fund but the asset is cheap I expect the fund to outperform a low cost index fund. For example, the table below shows the one year performance of the fund versus a low cost S&P 500 index fund.

The obvious flaw with my numbers is I assume both would reach their intrinsic value in one year but I wanted to quickly show my thinking.

Defense Companies

I bought a basket of Defense companies ($HII, $GD, $NOC, $LMT and $RTX) as a hedge against the world remaining peaceful and because they’re pretty cheap. In general, defense budgets remain high no matter which political party is in power.

I understand the logic of keeping these companies funded. If you keep your car in your garage for a year and you don’t use it. When you go to start it up its not going to run that smoothly. The same applies to defense companies. You don’t want these companies to fire a lot of people and then suddenly have to hire people back quickly.

Huntington Ingalls Industries is a duopoly and will probably grow 11-12% per year. It pays 2-3% dividend and their CEO is one of the largest shareholders (about $100 million worth of stock). Lockheed Martin has a $100 billion enterprise value and generates $5 billion in free cash flow, is trading at 13 times PE with a 3-4% dividend, which was raised. They just hired 10,000-11,000 people and they bought back $1 billion worth of stock.

Special Mention

Micron ($MU)- I’ve owned this stock for about two years and I have a 105% return. I realized I haven’t written about this company yet.

I have not sold any shares. I’m not going to lie and say it has been easy not to sell. The reason why I haven’t sold is the saying that, “you never got poor by taking profits, but you also didn’t get rich by selling.”

When I first made this investment it was pretty easy to make. First, the CEO is quite good with a proven track record. (Also, he’s an immigrant to America and I prefer CEOs who are immigrants because they appreciate the opportunity of the American Dream. In other words, I stated one of my biases.)

Second, in terms of evaluation I knew it was a cyclical and did a simple average Owners Earnings calculation and Micron was very cheap. Micron’s average ROE and ROIC from 2011-20 was 15.5% and 13.7% respectively.

The longer I’ve been a shareholder the more I realized Micron may have tremendous growth potential, which is being overlooked by the Market. Micron is in an oligopoly business and with AI becoming a bigger part of society I realized there will be a lot more DRAM needed. Some see Micron as a commodity business but the world is going to need a lot more of that commodity. Even at a $88 price point the forward PE of the stock is about 13-14, which means it’s still cheap.

Management did a lot of good things in 2020. For example, Micron (and Lockheed Martin) paid their suppliers early so the suppliers could keep making the components. A cynic would say Micron was paying early for their own benefit, which is could be true, but they easily could have behaved like Walmart and screwed their suppliers.

I recently read 100 Baggers and 100 to 1 in the Stock Market. They’re both fantastic and are must reads. Also Bill Gurly on the Entrepreneurs and Technology Podcast said, in regards to holding a stock, “the hardest thing to possibly do is just close your eyes and forget it. And the only thing analysis that’s going to cause you to do is sell the stock. You know, you — you’re not going to run analysis, you know, for the fourteenth time and go, hmmm, I should keep holding like that. And that is so hard, so, so hard to implement — easy to say, very hard to implement.”

I’ve been thinking a lot about elongating my hold periods. The data in the two books show that  in order to get a 100 bagger you need to hold for a long time; usually at least 10 years. So, in order to get those gains you have to have the fortitude to sit on your hands during high/low interest rate periods, recessions/depressions and unforeseen macroeconomic events.

Currently, I’m up 105% on Micron, which at the time was, on a cost basis, 10-11% of my portfolio. Micron is 15% of my portfolio. It’s been extremely tempting to trim the position, but I’m not touching it any time soon.

Conclusion

I’m fully invested. Moving forward I’m going to hold more cash and physical precious metals because in the next 2-6 years I think there is a 50-65% chance we get a bad recession or even a depression and I want to have ample liquidity to ride it out. In other words, I am moving forward but with caution. I believe its important to first hedge against both the left tail before trying to go after the right tail.

Posted in Investing | Leave a comment

2021 12-Team Mixed NFBC Draft Recap

This year I’m only doing one draft. Usually I two or three, but since I’m building a new house, I decided keeping extra cash was the most prudent thing to do. I’ve won at least one league in the past two seasons (I’m excluding 2020) and I think I’m going to win for a third year in a row.

League Background

This is a 12-team mixed NFBC draft. The roster consists of 14 hitters, nine pitchers and seven bench players. You set your pitchers once a week; hitters are set twice a week; waivers occur once a week.

Overall Thoughts

I never saw so much starting pitching taking in the first 2-3 rounds. Nine pitchers were taken in the first two rounds (37.5% of the picks) and 15 pitchers taken in the first three rounds (41.7% of the picks).

I think the rationale for the premium on pitching is if most, if not all, pitchers will have lower workloads then it’s better to get as many quality innings as possible. For example, in a normal year for fantasy a pitching staff may have 1,400 innings. But if workloads are decreased maybe there will only be 1,300 innings. If so, then those 180 innings of Jacob DeGrom will even more valuable because his innings represent a bigger part of the total.

That could be true, but I think in order to win you have to do A) do something different from the crowd and B) have your actions be correct. In other words, you want to be a contrarian, but you don’t want to be contrarian just to be contrarian.

My thesis was I want to stream pitchers all year because innings are going to be scarce. So, my plan was I wanted to dedicate five out of the seven bench spots to starting pitchers. To achieve this, I had to spend a lot of my early picks on hitters and I wanted to get two closers who should keep the job all year.

Lastly, in rounds 4-6 there were only six starting pitchers and three relievers taken. In those rounds owners were drafting hitting but I drafted two relievers and one hitter.

My Team

Below is my team with my projections; not listed are my bench players but they will be discussed below the images:

Individual Player Analysis

Trea Turner (#2) – Originally, I was going to take Fernando Tatis Jr. at the second spot, but there wasn’t that much difference between Tatis and Turner. Stolen bases will be scarce this year and that is the one edge Turner had. Also, Turner has a better health history.

Bryce Harper (#23) – With all the pitching taken Harper fell to me. When I was planning my draft I didn’t even consider him being available. I projected 12.5 stolen bases; I wouldn’t be shocked if he only steals 5-6.

Ozzie Albies (#26) – Albies was my top rated second baseman. I had Xander Bogaerts rated higher, but I already had a shortstop and I knew I was going to draft Paul DeJong later so I took the best player available that wasn’t a shortstop. For my projections I assumed Albies would hit second. There was chatter that Dansby Swanson would hit second, but that’s crazy talk. Swanson is a good real life player but he’s not the hitter Albies is.

Josh Hader (#47) & Edwin Diaz (#50) – Liam Hendricks was top closer but he was off the board so I took the top two closers remaining. My thesis for taking two closers is I get guaranteed saves with good ratios and a lot of strikeouts. There is risk with both pitchers; Hader will only pitch one inning, which reduces his strikeouts and Diaz may lose his job. Diaz walks too many guys and when men get on base for free bad things happen. In his last 84 innings he has a .379 BABIP. I have to assume the BABIP regresses and he has a high two’s/low three’s ERA with plenty of strikeouts.

The idea for drafting two legit closers was I wouldn’t have to use bench spots on potential closers and I wouldn’t have to use a lot of my FAAB on closers throughout the year. Lastly, if innings are less overall then the good ratios of the closers will be even more useful.

Sal Perez (#71) – You have to start two catchers and with the position being so bad, getting a top catcher is even more important. In the NFBC format you don’t want to wait for catching. For example, the worst catcher is far worse than the worst second baseman. You’re betting off paying for a top catcher and getting the other positions later on.

Byron Buxton (#74) – If he can play a full year he easily gets to 20/20. If he has a breakout he’s a 30/30 player.

Charlie Blackmon (#95) – I planned on taking Wil Myers in this spot but he wasn’t available. Blackmon biggest asset is the batting average. He will easily hit in the .290’s and could hit in the .300’s. He’s not going to steal bases but I’m not counting on him for that.

Tommy Edman (#98) – The biggest worry I had for Edman was Matt Carpenter taking at-bats from Edman. Well, Carpenter looks done and with Harrison Bader out Edman is going to play every day in the leadoff position. In 147 games Edman is hitting .283 with 16 home runs and 17 stolen bases. A lot of fantasy experts are down on Edman, but according to my data it’s not unreasonable he goes 20/20. Also, he has eligibility at four positions. That position flexibility will allow me more bench space for pitchers.

Nick Senzel (#119) – this is a purely a bet on Senzel’s raw talent and that the Reds hopefully leave him alone and let him play every day.

Miguel Sano (#122) – It seems like I draft him every year. Joey Gallo gets all the fantasy headlines but Sano has more power than Gallo. The new baseball this year won’t alter Sano’s power potential.

Zack Greinke (#143) – At this price point I’m not expecting him to be a top ten pitcher. He was 19th on my board and at this price I think I got a steal. It’s also possible the decline in fastball velocity makes him ordinary. Again, at the price I paid I think Greinke is worth it.

Jose Urquidy (#146) – This pick is purely on the raw stuff and the hope that being on a good team he can get more wins than if he were on a bad team.

Rhys Hoskins (#167) – Hoskins is not a good defensive first baseman but for fantasy that doesn’t matter. He’s going to hit fourth every day with a lot of power. His batting average will be low but that’s why I drafted someone like Blackmon.

Paul DeJong (#170) – How many shortstops can hit 25-30 home runs with a lot of RBI potential? Not that many. DeJong is a steal at this price.

Mitch Haniger (#191) – I’m hoping Haniger is finally healthy and can play in 150 games.

Jorge Polanco (#194) – Polanco will get second base eligibility after two weeks. Roster Resource has him batting fourth in a very good lineup. He does a little bit of everything. I projected a .283 batting average but I can easily see a .295 average. Also, if he drops to 5th in the lineup; I have Sano so either way I’m getting the 4th spot in the Twins batting order.

German Marquez (#215) – For my projections I assumed that all his starts would be on the road. As long as I stream Marquez I’ll get a lot of value. Also, it’s possible he’s traded which makes him even more valuable. The only downside is he probably won’t get a lot of wins because the bullpen being so bad.

Omar Navarez (#218) – I waited to get my second catcher because Navarez was my 11th rated catcher and he was going as the 20th catcher. I drafted him because of playing time and his batting average; a career .267; and he’s two years removed from 22 home runs.

Michael Pineda (#239) – Pineda is more of an accumulator at this point. He should provide a lot of innings with solid strikeouts, WHIP and hopefully wins. His stuff is good enough he could be a number two real life starter.

Kyle Schwarber (#242) – I was planning on taking a pitcher here but I couldn’t believe Schwarber was still available. Yes, he’s not a good defender and he doesn’t hit for average. But he has the power to hit 30-plus home runs and if someone gets hurt I can plug him in and still get my power. Also, he should hit fourth or fifth which means he’ll get a lot of RBIs.

Jordan Montgomery (#263) – see Michael Pineda.

Andrew Heaney (#266) – This is a bet purely on his stuff. If he takes the next step, he’s a real life number two starter.

Mike Minor (#287) – This is a bet purely on his stuff.

Eduardo Escobar (#290) – Escobar is always underrated. He’s going to hit fourth in the lineup and hit 20-25 home runs with a lot of RBI and a batting average that won’t hurt you. Also, I didn’t have another third baseman so I wanted to make sure I had a solid backup.

Mitch Keller (#311) – This is a bet purely on his stuff.

Anthony DeSclafani (#314) – For my projections I assumed all of his innings would be pitched at home. If I only stream him at home he should be a good backend starter.

Trevor May (#335) – May is a hedge for my Diaz pick.  

Chris Archer (#338) – Curious to see how he looks. 

Luke Weaver (#359) – Curious to see how he looks. 

Conclusion

Overall, I love my team. It’s far from perfect but I hit (pun intended) all my hitting thresholds and I have a pitching staff that if mixed and matched correctly and luckily, I should have a mediocre pitching staff.

Posted in Uncategorized | Leave a comment